Investment Properties and Land
Condo or house: which fits your investment plan in San Diego County?
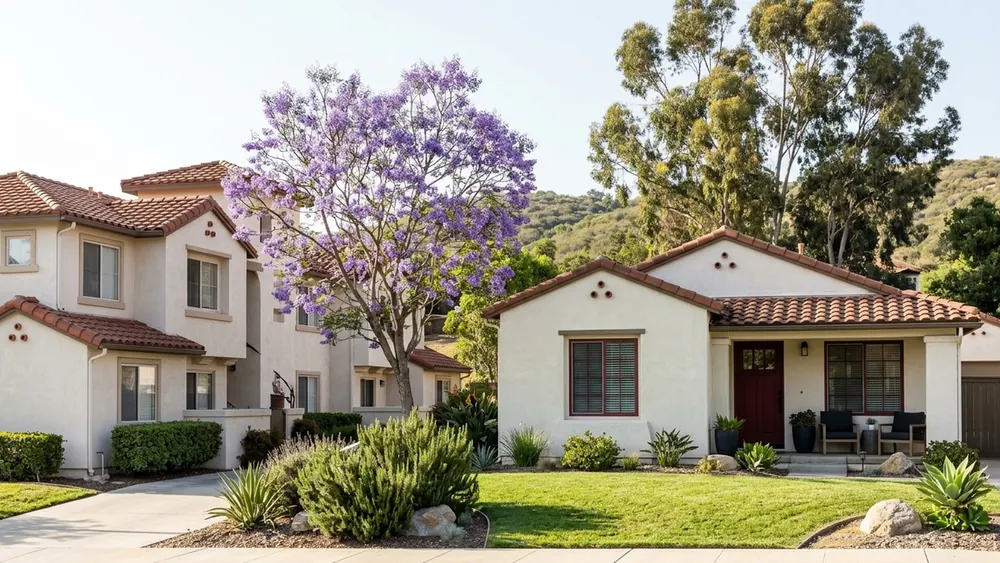
Neither a condo nor a house fits every investment plan. The right choice in San Diego County depends on association rules, upkeep, the full cost of ownership, how hands on you want to be and how long you plan to hold.
On this page
- The short answer on condo versus house
- Write the plan before you tour
- What association rules mean for condo owners
- What a rental house asks of you
- Questions that apply to either property type
- Comparing condos and houses side by side
- Assumptions that can tilt the choice
- Your next step toward a decision
The short answer on condo versus house
There is no universal answer, and anyone who gives one is skipping your plan. A condo or a house can each fit an investment, depending on the rules that apply, the upkeep you are willing to carry, the full cost of owning it and how long you expect to hold it. The useful question is not which type is stronger in general, but which one fits the plan you have actually written down for San Diego County.
The framing matters because condos and houses move cost and control in different directions. With a condo, an association often handles some exterior upkeep and shared areas, and in return you pay dues and follow its rules, including rules about renting. With a house, you usually control more and carry more, from the roof to the yard. Neither is automatically easier. Each one simply places work and risk somewhere different.
So the decision starts with you rather than the property. How much time do you want to spend on maintenance? How comfortable are you living with rules someone else sets? How much cash do you want held in reserve? Once those answers are on paper, comparing a condo in Carlsbad with a house in Oceanside, or any two properties across North County San Diego, becomes a matter of matching facts to your plan.
Write the plan before you tour
Before you compare properties, write a short plan. Note whether you intend to rent long term, move in later or hold the property while you decide. Note how hands on you want to be and whether you would hire property management. Those choices shape which type fits. A buyer who wants less exterior upkeep may lean one way, while a buyer who wants more control over renting may lean the other.
Your plan also sets the assumptions you will test. Write down the costs you expect, the reserve you want to keep and what would make you walk away. Then measure every property against that same page, so a well staged condo or a generous yard does not pull you off your own priorities. Keeping the plan in writing is the simplest way to stay steady when two very different properties both look appealing.
I ask every investor the same first question: what does your plan need from this property? The property type comes second, once the plan is on paper.
What association rules mean for condo owners
If you are considering a condo, the association’s governing documents may matter as much as the unit. They can address whether units may be rented, minimum lease terms, limits on how many units can be rented at once, tenant approvals and rules for shared areas. Ask for the documents early and read the leasing sections closely. A unit that fits your budget does little for you if its rules do not fit your plan.
Look at the association’s finances as well. Ask about current dues, any history of special assessments, the reserves it holds and any pending projects or disputes. Those are questions for the association, and a qualified legal professional can help you read what the documents actually say. Write down every answer with the date and the source, because rules and dues can change after you buy, and you want to know how changes get made.
Say a condo you are weighing has an association with strict rental rules. That one detail could rule it out for a rental plan while leaving it workable for someone who intends to live there later. The same building can suit one plan and not another, which is why the documents come before the decision. Reading them early also keeps you from paying for inspections on a unit your plan cannot use.
What a rental house asks of you
A house usually means fewer shared rules and more personal responsibility. You may control decisions about tenants, improvements and upkeep, within city, county and state rules, and a house in a planned community, whether in Carmel Valley, 4S Ranch or elsewhere, may still have an association with rules of its own. Ask whether one exists before assuming you are free of one, then confirm the rental rules through official sources.
With a house, the repair list belongs to you. Roofs, systems, landscaping and exterior surfaces all become lines on your worksheet, and a licensed home inspector is the right person to describe their condition. An insurance agent can explain coverage for a rental house, which may differ from coverage for a condo. Planning a reserve for these items is part of the decision itself, not something to sort out after closing.
Questions that apply to either property type
Whichever way you lean, some questions apply to both. Answering them for every property you consider puts a condo and a house on equal footing, so you compare facts rather than impressions. Keep the answers on one worksheet with the source noted beside each, so you can see at a glance where a property fits your plan and where it still has open questions.
- Which rental rules apply, confirmed with the association and official sources
- What the full monthly cost of ownership would be, line by line
- What condition the property is in, according to a licensed home inspector
- How the purchase would be financed, as explained by a licensed lender
Financing deserves its own note. Loan options for an investment property can differ from those for a home you live in, and a condo may be reviewed differently from a house. Michelle Peters describes a background in mortgage and financing work and can explain these concepts plainly, but rates, terms and whether a particular property or borrower qualifies are questions for a licensed lender. Ask before you narrow the search, not after.
Comparing condos and houses side by side
It helps to set the two property types next to each other on the questions that matter most to an investment plan. The table below is not a verdict. It shows where condos and houses often differ, and who can confirm the details for the specific property in front of you. Add your own notes beside each row as answers come in, and add any rows your plan calls for.
| Topic | Condo | House |
|---|---|---|
| Rental rules | Association documents plus city or county rules | City or county rules, plus any association |
| Exterior upkeep | Often shared through association dues | Usually your responsibility and your reserve |
| Monthly costs | Loan, taxes, insurance and association dues | Loan, taxes, insurance and ongoing upkeep |
| Day to day control | Many decisions shared with the association | More decisions are yours to make |
| Who confirms details | Association, legal professional and licensed lender | Home inspector, insurance agent and licensed lender |
Use the table as a prompt for questions, not a set of answers. Every property is its own case. A house in a planned community can behave a lot like a condo, while some condo associations leave more to the owner than you might expect. The only reliable answers come from the documents, the inspection, the insurance quotes and the lender for the property you are actually considering.
Assumptions that can tilt the choice
Several assumptions tend to tilt this decision without ever being tested. One is that dues cover more than they really do. Another is that a house never has an association. A third is that today’s rental rules will stay in place. A fourth is that upkeep on a house will stay modest because it looks well kept today. Each of these is a question to verify, and none should be taken as given.
The answer is not predicting which property will perform, because no one can promise that. It is testing your plan against cautious versions of your worksheet. What happens if dues rise, if a repair arrives early or if a unit sits empty for a while? If one property type still fits your goals under those versions and the other does not, the decision becomes much clearer.
Your next step toward a decision
Before a first conversation, write down your plan, the cash you are comfortable committing, how hands on you want to be and the areas you are curious about, anywhere across North County San Diego. Gather any association documents or listings you have already seen, and note the questions still open on each one. That short packet is enough to start a useful conversation.
Then bring it to Michelle at HomeSmart Realty West. Let’s look at what actually makes sense for you: which property type fits the plan, what to check on each candidate and which questions belong to a licensed lender, a real estate attorney or the association. There is no pressure and no deadline. A clear, numbers aware decision is the whole point, and it starts with the plan you already wrote down.
This article is general information about selling, buying, investing and relocating across North County San Diego and San Diego County. It is not legal, tax, lending, zoning or inspection advice and does not predict prices or returns or promise results. Confirm financing with a licensed lender, contracts with a qualified legal professional, and zoning, land use, taxes and services with official sources. Michelle Peters, HomeSmart Realty West.
Written by